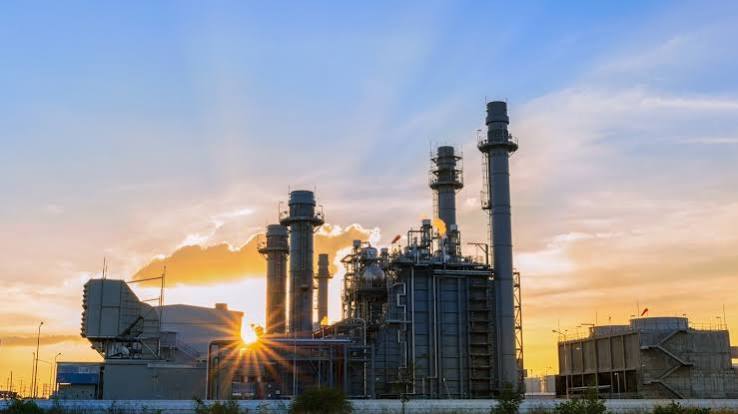
CPV Group is consolidating the financing of two natural-gas power plants in the U.S. Mid-Atlantic under an $825 million agreement, refinancing existing project debt and creating room for an approximately $130 million distribution to the power producer.
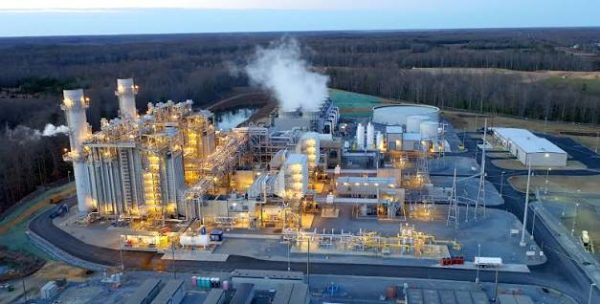
The financing covers the 725-megawatt (MW) Shore Energy Center in New Jersey and the 745-MW Maryland power plant in Waldorf, Maryland. Both facilities operate as natural-gas-fired combined-cycle power plants in the PJM electricity market, giving CPV a combined generating portfolio of 1,470 MW under the transaction.
CPV Generation Holdings LLC, an indirect wholly owned subsidiary of CPV Group, entered into the financing agreement with a syndicate of lenders on October 27, 2026. OPC Energy, which owns approximately 71% of CPV Group, announced the transaction on October 29.
The new arrangement replaces the plants’ separate project-level financing structures with a consolidated facility. It also reduces the interest spread on the main term loan from 3.25% to 2.5% above the Secured Overnight Financing Rate (SOFR), lowering the margin by 75 basis points.
The transaction does not finance a new power plant or add generating capacity. Instead, it restructures the debt attached to two operating electricity-generating assets.
Two power plants, one financing structure
The transaction brings together two facilities that serve the PJM electricity market but occupy separate locations.
The Shore Energy Center is a 725 MW combined-cycle natural-gas power plant in Woodbridge Township, New Jersey. The Maryland facility, known as the St. Charles Energy Center, has 745 MW of generating capacity and operates in Waldorf, Charles County.
Combined-cycle plants use natural gas to power a gas turbine and then recover heat from the turbine’s exhaust to produce steam for a second turbine. This arrangement extracts additional electricity from the same fuel input compared with a simple-cycle gas turbine.
The two plants are therefore existing generation assets rather than developments awaiting construction or commercial operation.
Their combined 1.47 GW capacity also gives the financing a substantial footprint in the PJM Interconnection market, which coordinates wholesale electricity across parts of the Mid-Atlantic and Midwest.
CPV’s ownership consolidation preceded the refinancing
The financing follows a series of ownership changes that gave CPV full control of both generating facilities.
CPV acquired the remaining approximately 11% interest in the Shore plant in January 2026. It subsequently acquired the remaining 25% interest in the Maryland plant in May 2026.
Those transactions brought both plants under full ownership by CPV Group before the company moved to consolidate their financing.
The distinction between asset ownership and parent-company ownership is important. CPV Group owns the plants, while OPC Energy holds approximately 71% of CPV Group. The refinancing is therefore part of a broader portfolio strategy involving an Israeli-listed energy company and its U.S. generation subsidiary.
OPC has described greater ownership and control of its U.S. generating assets as a way to capture operational and financial efficiencies across its portfolio.
The company also referenced Basin Ranch, another U.S. power plant over which CPV has achieved full ownership and control, as part of this strategy.
How the $825 million financing is structured
The agreement combines long-term borrowing with credit facilities that support the plants’ operational and collateral requirements.
The largest component is a $625 million Term Loan B, carrying an interest margin of 2.5% above SOFR and a seven-year maturity. The loan has no scheduled amortization, although mandatory repayments can be triggered through a cash-flow sweep mechanism tied to leverage ratios.
The remaining facilities comprise a $125 million letter-of-credit facility and a $75 million revolving credit facility.
The letter-of-credit facility supports collateral requirements associated with the plants, while the revolving facility can provide cash borrowings or additional letters of credit. Both have five-year terms.
The facilities should not be confused with $825 million in immediately available construction capital. The total represents the principal amount of the financing package, including credit commitments that may be used for different purposes.
The main term loan also has a different cost structure from the previous project debt. Reducing its spread from 3.25% to 2.5% above SOFR means CPV will pay a smaller margin over the benchmark rate, although the actual borrowing cost will continue to depend on SOFR.
The agreement is secured by first-ranking pledges over the two projects and their assets, as well as a pledge over the equity interests in the borrowing entity. It also includes customary financial covenants and restrictions on additional debt, asset sales and distributions.
Refinancing will support a $130 million dividend
Beyond repaying existing project debt, the financing is expected to fund a dividend distribution of approximately $130 million to CPV Group at closing.
This makes the transaction more than a straightforward refinancing. It allows the owner to extract capital from two established power-generation assets while replacing their existing debt arrangements with a new consolidated financing structure.
The dividend is not an additional investment in the plants, nor does it represent new electricity-generation capacity.
Financial details reported by Israeli business publication Calcalist indicate that OPC could receive approximately $92 million of the distribution through its 71% ownership interest in CPV Group. The amount remains dependent on the actual distribution and applicable corporate arrangements.
The refinancing also extends the term of the main borrowing arrangement to seven years, giving the company a longer financing horizon than the previous debt attached to the facilities.
However, the financing agreement remains subject to customary conditions precedent to closing. The announced terms should therefore be distinguished from a confirmation that all funds have already been disbursed.
What the transaction means for CPV’s U.S. generation portfolio
The refinancing reflects the financial strategy behind CPV’s growing ownership of U.S. electricity-generation assets.
Rather than developing additional capacity through this particular transaction, the company is reorganizing the capital structure of two existing plants to reduce borrowing costs, support operational requirements and release capital to its parent group.
The facilities also operate in the PJM market, where natural-gas generation forms part of the electricity supply mix alongside nuclear, coal, renewable energy and other resources.
Their combined 1,470 MW capacity gives CPV a substantial operating position in the region, although the refinancing itself does not change their installed generating capacity.
For OPC, the agreement provides a way to manage the financing of its U.S. portfolio through a consolidated structure while retaining ownership of the underlying generation assets through CPV.
The next important milestones are the satisfaction of the financing agreement’s closing conditions, repayment of the existing project debt and completion of the planned dividend distribution.
While investment in existing power-generation assets remains important to the U.S. electricity market, the country’s energy infrastructure is also expanding through new domestic manufacturing capacity. SEG Solar, for example, has outlined a $950 million investment in a 4 GW heterojunction solar cell manufacturing facility at its Tomball Industrial Campus in Texas. The proposed development would bring solar cell production alongside module manufacturing, strengthening the domestic supply chain for solar equipment.
Factsheet: CPV Group natural-gas-fired combined-cycle power plants in New Jersey and Maryland
- Transaction: Consolidated financing and refinancing of two U.S. power plants
- Borrower: CPV Generation Holdings LLC
- U.S. operating group: CPV Group
- Parent company: OPC Energy
- OPC’s ownership in CPV Group: Approximately 71%
- Total financing: $825 million
- Term Loan B: $625 million
- Letter-of-credit facility: $125 million
- Revolving credit facility: $75 million
- Planned dividend: Approximately $130 million
- Term loan maturity: Seven years
- Term loan interest margin: SOFR plus 2.5%
- Previous interest margin: SOFR plus 3.25%
- Shore Energy Center: 725 MW, Woodbridge Township, New Jersey
- Maryland / St. Charles Energy Center: 745 MW, Waldorf, Maryland
- Combined generating capacity: 1,470 MW
- Fuel: Natural gas
- Generation technology: Combined cycle
- Electricity market: PJM Interconnection
- Agreement date: October 27, 2026
Leave a Reply